x



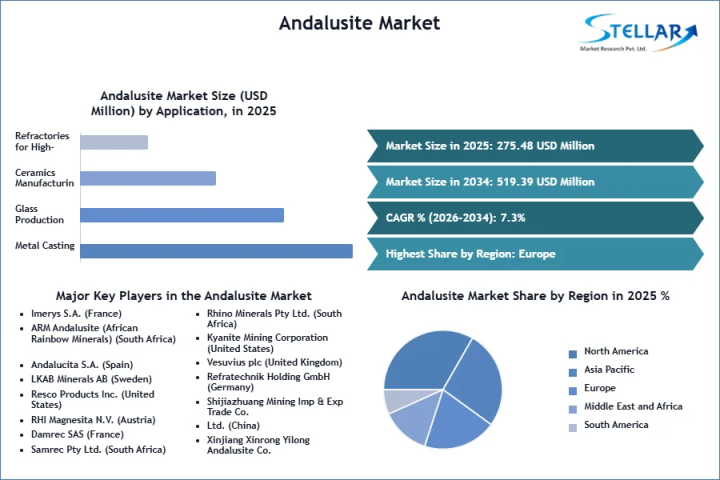
The global Andalusite Market is experiencing a pivotal structural transformation, driven by green steel initiatives, furnace efficiency demands, and critical mineral supply chain realignments, according to the latest multi-sector intelligence report by Stellar Market Research. Valued at USD 286.5 Million in 2025, the global market is projected to reach USD 438.2 Million by 2032, expanding at a compound annual growth rate (CAGR) of 6.2% over the forecast period (2026–2032).
As heavy industrial sectors—most notably steelmaking, cement, and advanced ceramics—accelerate their transition toward low-emission manufacturing, andalusite has emerged as an indispensable mineral feedstock. Renowned for its natural conversion to mullite at high temperatures without volume change, the mineral significantly lowers energy consumption during refractory manufacturing while extending the lifespan of extreme-heat industrial kilns.
Dominant Application: Refractory manufacturing commands more than 62% of global volume, propelled by structural demand across iron, steel, and foundry operations.
Fastest-Growing Segment: Technical Ceramics and Raw Andalusite are expanding at a 7.1% CAGR, fueled by wear-resistant component fabrication in electronics and automotive engineering.
Regional Dominance: Asia-Pacific retains market leadership with a 42% global share, anchored by continuous expansion in Indian and Southeast Asian steel production corridors.
Emerging Frontier: North America is exhibiting the fastest regional growth trajectory, spurred by critical raw materials mandates and aggressive modernizations of domestic foundry infrastructure.
Operational Efficiency Gains: Integration of AI-driven optical sorting during mineral beneficiation has improved batch consistency by 18%, reducing end-user material scrap rates by 12%.
Investment Relevance: Long-term off-take contracts and direct mine-to-manufacturer supply partnerships have surged by 30% over the past 18 months as steelmakers secure critical supply lines.
Transition to Low-Carbon Steelmaking: The global expansion of Electric Arc Furnaces requires refractories with superior thermal-shock resistance and minimal volumetric expansion, placing andalusite at the core of green metallurgy.
Surge in Technical Ceramics Manufacturing: Increasing production of specialized electrical insulators, wear-resistant seals, and structural ceramics requires consistent high-alumina raw inputs.
Infrastructure & Cement Kiln Modernization: Rapid urban expansion across emerging economies is elevating demand for high-efficiency refractory linings in continuous-run cement kilns.
Geographic Concentration Risk: Over 70% of global commercial deposits are localized in South Africa and France, exposing international buyers to geopolitical and intermodal freight disruptions.
High Beneficiation Capital Costs: Advanced magnetic and optical separation equipment demands substantial upfront capital investment, restricting entry for small-scale mineral processors.
Sustainability mandates in North America and Europe are forcing heavy industrial plants to account for Scope 1 and Scope 2 emissions. Raw andalusite allows manufacturers to eliminate the energy-intensive pre-calcination step required by synthetic refractories, providing an immediate pathway toward ESG compliance. Additionally, processing plants are incorporating AI- and IoT-enabled quality inspection lines to ensure uniform grain density, satisfying stringent aerospace and metallurgical standards.
Asia-Pacific continues to lead global consumption, with China and India accounting for the bulk of industrial demand. India’s aggressive national steel capacity targets are spurring major domestic refractories to scale beneficiation plants. Meanwhile, North America and Europe are seeing accelerated adoption due to regulatory incentives supporting clean manufacturing and critical minerals resilience, with domestic foundries upgrading furnace linings to meet stricter grid-efficiency standards.
Imerys S.A. (2025): Expanded extraction and beneficiation capacity at its South African operations by 15%, integrating solar-assisted processing to cut site carbon intensity by 20%.
LKAB Minerals (2025): Launched a novel ultra-pure milled andalusite grade targeted specifically at high-precision 3D refractory molding and investment casting applications.
Andalusite Resources (2024): Commissioned an automated optical sorting plant in Limpopo, raising material recovery rates by 14% while reducing water consumption per metric ton processed.
Sibelco (2025): Entered a strategic off-take partnership with European refractory producers to secure supply lines for low-carbon aluminosilicate minerals through 2030.
Damrec / Imerys Group (2024): Successfully piloted a closed-loop recycling program for spent andalusite furnace linings, achieving a 15% reduction in raw ore extraction requirements for industrial customers.
The global market remains consolidated among established mineral specialists, including Imerys S.A., Andalusite Resources, LKAB Minerals, Sibelco, Kyanite Mining Corporation, Damrec, and Picobello Andalusite. Leading vendors are prioritizing capacity expansions, automated beneficiation technologies, and strategic off-take agreements with global steel conglomerates to protect market share against synthetic substitute producers.
"The andalusite sector is no longer viewed simply as a niche industrial minerals market; it has become a strategic enabler of industrial decarbonization," said a Senior Research Analyst at Stellar Market Research. "As steelmakers and ceramic producers face escalating pressure to lower energy consumption and carbon emissions, the natural energy-saving properties of andalusite offer an immediate, cost-effective solution. Over the forecast period, we anticipate a sharp rise in vertical integration, with end-users taking direct equity stakes in mineral processing assets to lock in high-purity supply."
Through 2032, the market will be characterized by automated processing, eco-friendly calcination techniques, and tighter integration between mineral miners and steel manufacturers. As industrial facilities transition to smart-furnace technologies, demand for high-purity, standardized andalusite formulations will outpace standard commercial grades, creating premium margin opportunities for technology-forward suppliers.
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656