x



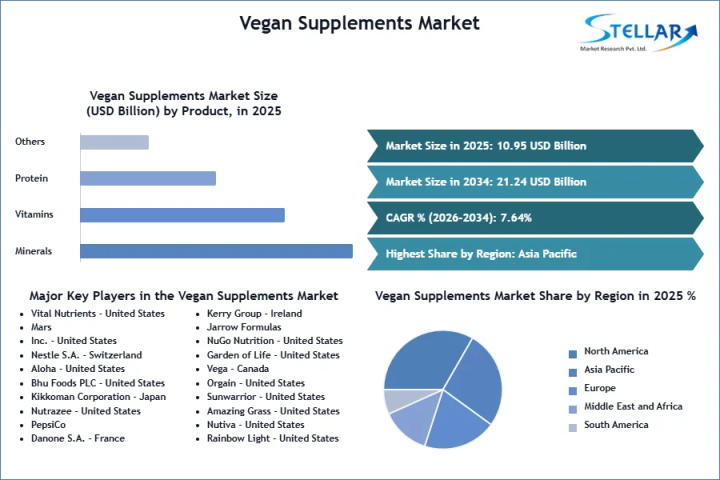
The Global Vegan Supplements Market is undergoing a structural transformation as non-animal functional nutrition transitions from a niche lifestyle choice into a mainstream clinical wellness imperative, according to the latest multi-sector intelligence report published by Stellar Market Research. Valued at USD 9.45 Billion in 2023, the global market is projected to expand at a Compound Annual Growth Rate (CAGR) of 7.64%, scaling to USD 15.82 Billion by 2030.
Driven by a rapid surge in global flexitarianism, heightened clinical awareness around micronutrient deficits, and bio-fermentation breakthroughs, the market is experiencing unprecedented institutional investment. Consumer demand is shifting from generic multi-vitamins toward high-bioavailability, clean-label formulations engineered to replace traditional animal-derived nutrients without compromising absorption efficiency.
Market Valuation & Growth: The global Vegan Supplements Market will add over USD 6.37 Billion in incremental revenue between 2024 and 2030, sustained by a steady 7.64% CAGR.
Product Segment Leadership: Vitamins and Minerals represented the largest revenue share in 2023, driven by universal demand for Vitamin B12, Vitamin D3 (derived from lichen), and chelated iron formulations.
Form Factor Dynamics: Capsules and tablets maintain dominant market volume, but Gummies and Chews represent the fastest-growing form factor due to widespread pill fatigue and rapid consumer adoption across younger demographics.
Ingredient Innovation: Microalgae-derived Omega-3 (EPA/DHA) oils are experiencing the highest growth acceleration within raw material segments, displacing traditional fish oil supplies threatened by marine depletion and heavy metal contamination concerns.
Distribution Channels: While physical drugstores and hypermarkets account for over 52% of traditional point-of-sale transactions, online pharmacies and DTC subscription platforms are expanding at a higher growth rate.
Regional Dominance: North America led the global market in 2023 with a share exceeding 38%, while the Asia-Pacific region is charted to experience the fastest CAGR through 2030.
Accelerating Shift to Flexitarianism & Preventive Healthcare: Millions of consumers worldwide are adopting semi-vegetarian diets, seeking plant-based supplements to fill nutritional gaps without fully committing to a strict vegan diet.
Advancements in Fermentation & Microalgae Extraction: Breakthroughs in industrial bio-fermentation allow manufacturers to synthesize bioactive nutrients like B12, Vitamin K2, and amino acid complexes at higher purities and lower production footprints.
ESG-Driven Consumer Preferences: Environmental concerns surrounding ocean fishing (for marine oil) and intensive livestock production are pushing consumers toward verified, cruelty-free, carbon-neutral supplement alternatives.
High Raw Material Extraction Costs: Microalgae farming and liposomal processing require significant capital expenditure, resulting in a 20% to 35% cost premium on shelf prices over standard synthetic or animal-derived equivalents.
Regulatory Fragmentation & Labeling Ambiguity: The absence of a unified global regulatory framework defining "vegan supplement" standards leaves room for cross-contamination risks and label claims scrutiny across international borders.
Technological convergence is redefining plant-based nutrient delivery. Liposomal technology and microencapsulation are now widely applied to protect sensitive plant enzymes, probiotics, and botanical extracts from degradation in gastric acid, boosting intestinal absorption.
From a regulatory perspective, watchdog bodies including the U.S. FDA and European Food Safety Authority (EFSA) are enforcing strict traceability mandates regarding heavy metal limits, botanical purity, and synthetic solvent residues in plant extractions. Simultaneously, ESG compliance is dictating supply chain structures; leading brands are abandoning petroleum-based blister packaging in favor of compostable pouches, ocean-bound recycled plastic containers, and refillable glass systems.
North America remains the dominant revenue engine, anchored by high disposable income, well-established retail pharmacy chains, and aggressive product diversification by key players in the United States and Canada. Consumer demand in this region is heavily centered on functional wellness, sports nutrition, and clean-label verification.
Asia-Pacific represents the fastest-growing regional market over the forecast period. Rapid urbanization, rising personal health expenditure, and deeply rooted botanical wellness traditions across China, India, Japan, and South Korea are powering regional demand. Furthermore, expanding local manufacturing infrastructure in India and China is driving down production costs for plant proteins and herbal extracts, accelerating regional commercialization.
Nestlé Health Science / Garden of Life (2023): Expanded its organic, non-GMO vegan multi-vitamin portfolio with a targeted liposomal B12 spray, increasing nutrient absorption rates by an estimated 30%.
Archer Daniels Midland (ADM) (2023): Invested USD 30 Million in scaling its precision bio-fermentation facilities to manufacture high-purity, plant-sourced functional amino acids for sports nutrition applications.
Kerry Group plc (2024): Partnered with microalgae biotechnology specialist Fermentalg to launch an eco-certified, high-potency vegan Omega-3 DHA/EPA liquid solution for functional beverage and supplement applications.
NOW Foods (2024): Upgraded 100% of its plant-derived supplement lines to feature solar-powered manufacturing facility verification and fully recyclable PCR (post-consumer recycled) bottles.
Herbalife Nutrition (2024): Launched its plant-based V-Nourish line in key Asia-Pacific markets, targeting urban consumers with localized botanical formulations and allergen-free pea-and-rice protein bases.
The global market exhibits a blend of established multinational consumer health giants and agile, pure-play plant nutrition pioneers. Tier-1 players are focusing on vertical integration, strategic M&A to acquire bio-fermentation capabilities, and third-party certifications (such as The Vegan Society and Non-GMO Project Verified) to build brand equity.
Prominent organizations shaping market dynamics include:
Nestlé Health Science (Garden of Life, Atrium Innovations)
Danone S.A.
Archer Daniels Midland Company (ADM)
Kerry Group plc
NOW Foods
Sunwarrior
Herbalife Nutrition
GNC Holdings, LLC
Pharbio Nutrition
NutraShoppe Inc.
"The vegan supplements space has evolved far beyond basic dietary substitution; it is now a primary testing ground for advanced ingredient delivery systems," said a Senior Research Analyst at Stellar Market Research. "As consumers demand total transparency, zero animal impact, and verified clinical efficacy, brands that master precision fermentation and sustainable microalgae sourcing will capture long-term pricing power and customer loyalty over the next decade."
Through 2030, the global Vegan Supplements Market will be shaped by personalization and cellular-level nutrition. Artificial intelligence (AI) integration in direct-to-consumer health platforms is expected to enable customized vegan supplement regimens based on personal biomarker testing and gut microbiome analysis. As production efficiencies lower the cost of microalgae farming and bio-fermentation, price parity with conventional supplements will likely be achieved, unlocking mass-market adoption across emerging economies.
About Stellar Market Research: Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656