x



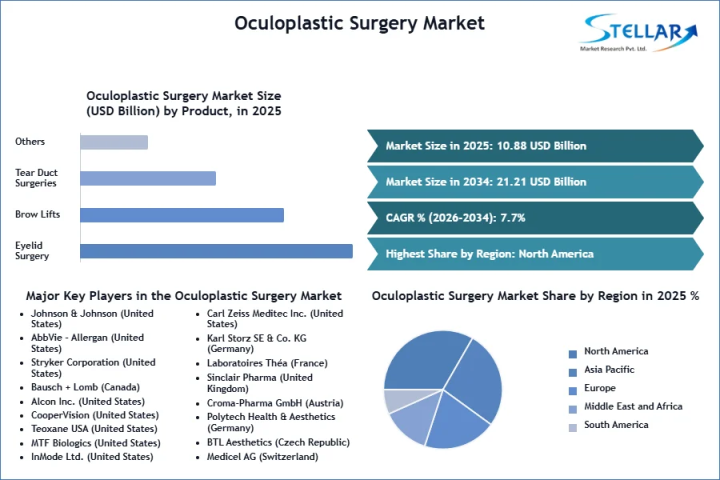
The global Oculoplastic Surgery Market is undergoing a profound structural evolution, expanding from USD 10.62 billion in 2025 to USD 11.27 billion in 2026, and is projected to scale to USD 18.15 billion by 2034. According to comprehensive market intelligence published by Stellar Market Research, the sector will demonstrate a resilient Compound Annual Growth Rate (CAGR) of 6.14% over the 2026–2034 forecast period.
Market Valuation & Trajectory: The global oculoplastic surgery market is valued at USD 11.27 billion in 2026 and will reach USD 18.15 billion by 2034, growing at a 6.14% CAGR.
Dominant Procedure Segment: Eyelid Surgery commands the market with approximately 38% revenue share, supported by stable reimbursement frameworks for medically documented visual field obstructions caused by ptosis and dermatochalasis.
Fastest-Growing Procedure Segment: Brow & Forehead Lift procedures represent the fastest-growing surgical category, expanding at an 8.64% CAGR, propelled by endoscopic micro-incision platforms and bio-absorbable fixation systems.
Dominant End-User Segment: Hospitals retain 54.47% share due to their capacity to manage high-acuity orbital trauma, pediatric malformations, and complex oncology cases requiring multidisciplinary surgical teams.
Fastest-Growing End-User Segment: Ambulatory Surgical Centers (ASCs) are compounding at 9.11% CAGR, driven by favorable outpatient reimbursement policies and lower operational overhead.
Regional Dynamics: North America dominates the global landscape with 36.25% market share, while Asia-Pacific is projected as the fastest-growing regional market, advancing at a 7.55% CAGR.
Expanding Geriatric Population with Functional Visual Impairments: The global surge in individuals aged 60 and older—projected by the WHO to reach 2.1 billion by 2050—is generating a massive cohort requiring functional blepharoplasty and ectropion/entropion repair to restore peripheral visual fields and ocular surface health.
Clinical Integration of Biologics for Thyroid Eye Disease (TED): The adoption of targeted biologic therapies has transformed TED management. By reducing acute phase tissue inflammation, biologics enable surgeons to perform precise, timed orbital decompressions and eyelid retractions with lower rates of surgical diplopia and surgical revision.
Technological Advancements in Energy-Based Microsurgery: High-precision radiofrequency and laser-assisted surgical tools allow for meticulous tissue dissection, instant coagulation, and minimal postoperative bruising, significantly reducing procedure times and boosting patient turnover.
Shortage of Fellowship-Trained Oculoplastic Surgeons: Oculoplastic surgery requires rigorous dual training in ophthalmology and plastic surgery. A global shortfall of specialized surgeons—particularly across developing regions—creates severe procedural bottlenecks and extended patient wait times.
Reimbursement Scrutiny and Coding Complexities: Strict insurance documentation standards demand rigorous visual field testing and photographic evidence to prove medical necessity, creating administrative burdens and occasional coverage denials for functional eyelid surgeries.
AI-Assisted Pre-Operative Digital Planning: Pre-operative 3D facial mapping and AI-driven predictive modeling software are enabling surgeons to simulate post-surgical eyelid symmetry and orbital volumetric outcomes, improving surgical accuracy and reducing revision rates.
Adoption of Human Umbilical-Cord & Amniotic Grafts: Oculoplastic procedures increasingly utilize bio-engineered human amniotic grafts to reduce postoperative inflammation, lower scarring, and accelerate mucosal healing in complex lacrimal and conjunctival reconstructions.
ESG & Outpatient Operational Transformation: Ambulatory surgical facilities are streamlining supply chains through reusable high-precision surgical instrument kits and eco-friendly sterilization workflows, directly aligning with healthcare ESG compliance mandates.
North America: Leading the global market with a 36.25% share, North America benefits from high per-capita healthcare expenditure, robust Medicare reimbursement structures for functional eyelid conditions, and a high concentration of specialized academic centers (e.g., Johns Hopkins Wilmer Eye Institute and Massachusetts Eye and Ear). The U.S. accounts for 87% of the regional market.
Europe: Holding approximately 28% global revenue share, Europe's market growth is supported by universal healthcare coverage for reconstructive procedures across Germany, the UK, and France. Germany accounts for 23% of European market revenue, driven by strong surgical instrument manufacturing hubs like B. Braun Melsungen.
Asia-Pacific: Highlighted as the fastest-growing region with a 7.55% CAGR, Asia-Pacific demand is fueled by expanding healthcare infrastructure in China and India, a booming medical tourism sector in South Korea and Thailand, and a rapidly rising middle-class demographic seeking both functional eye care and aesthetic periorbital procedures.
Bausch + Lomb (2025): Acquired specialized surgical product assets to expand its dedicated ophthalmic and oculoplastic portfolio, reinforcing its supply channel to outpatient eye surgery centers.
Carl Zeiss Meditec AG (2025): Launched an advanced digital visualization and microsurgical microscope suite featuring integrated intraoperative optical coherence tomography (OCT) for ultra-precise periorbital tissue dissection.
Rohrer Aesthetics, Inc. (2024): Introduced the PIXEL8-PRO RF platform, tailored for minimally invasive laser blepharoplasty and non-surgical periorbital skin tightening.
Integra LifeSciences Corporation (2024): Expanded its regenerative tissue portfolio by acquiring specialized amniotic tissue graft lines designed to improve ocular surface reconstruction and reduce post-surgical scarring.
Alcon Inc. (2024): Upgraded its surgical instrumentation ecosystem with specialized micro-forceps and precise electrosurgical tools tailored for delicate eyelid malposition and lacrimal duct repair.
The global oculoplastic surgery market features a consolidated-to-medium market structure dominated by established medical device manufacturing giants, specialized ophthalmic instrument developers, and regenerative biomaterial providers. Leading market players include:
Carl Zeiss Meditec AG
Bausch + Lomb
Stryker Corporation
Integra LifeSciences Corporation
B. Braun Melsungen AG
Karl Storz SE & Co. KG
Katena Products (Blink Medical)
TEKNO-MEDICAL Optik-Chirurgie GmbH
Key competitive strategies revolve around portfolio expansion through strategic M&A, developing specialized single-use micro-instruments, integrating high-definition digital visualization systems, and forming clinical training partnerships with global ophthalmic societies to expand surgeon proficiency.
"The oculoplastic surgery market is witnessing a fundamental convergence of functional ophthalmic reconstruction and cosmetic periorbital enhancement," stated a Senior Research Analyst at Stellar Market Research. "As procedure delivery rapidly shifts from traditional hospitals to specialized ambulatory surgical centers, equipment vendors and surgical device manufacturers must pivot toward modular, high-precision micro-instrumentation and AI-integrated visualization suites that optimize surgeon workflow and maximize throughput in outpatient settings."
Through the 2026–2034 forecast period, the oculoplastic surgery market will be characterized by accelerated technological integration and delivery-model modernization. The adoption of energy-based surgical devices, custom patient-matched orbital implants, and regenerative tissue matrices will further diminish procedural invasiveness. Simultaneously, expanding reimbursement coverage for functional visual impairment in emerging Asian and Latin American economies will unlock significant uncaptured demand, solidifying oculoplastic surgery as a high-growth pillar within global ophthalmic healthcare.
Stellar Market Research is a multifaceted market research and consulting company with professionals from several industries. Some of the industries we cover include medical devices, pharmaceutical manufacturers, science and engineering, electronic components, industrial equipment, technology and communication, cars and automobiles, chemical products and substances, general merchandise, beverages, personal care, and automated systems. To mention a few, we provide market-verified industry estimations, technical trend analysis, crucial market research, strategic advice, competition analysis, production and demand analysis, and client impact studies.
Address
Phase 3, Navale IT Zone, S.No. 51/2A/2, Office No. 202, 2nd floor, Near, Navale Brg, Narhe, Pune, Maharashtra 411041
Email
sales@stellarmr.com
Mobile
+91 9607365656