x


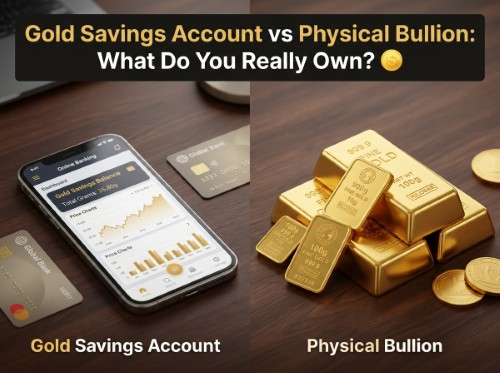
Many major retail banks offer convenient financial products known as "gold savings accounts". Through a standard mobile banking app, you can buy, hold, and sell gold denominated in grams at the click of a button. It feels seamless, modern, and identical to owning physical precious metals.
However, beneath the smooth user interface lies a fundamental structural difference. The distinction comes down to one critical question that every investor should ask before allocating their hard-earned capital: what, precisely, do you legally own?
A bank’s gold savings account is ultimately a bank liability—a digital entry on a ledger that tracks the spot price of gold. In contrast, a true physical bullion savings programme grants direct legal ownership of physical, allocated metal held safely outside the fractional banking system.
A gold savings account is a specialized banking product that allows retail customers to buy and sell gold-price-linked balances directly through their existing online banking portals. The account balance is typically denominated in grams rather than fiat currency, fluctuating in real time alongside international bullion spot prices.
It is crucial to distinguish between a gold savings account and saving in gold:
How Bank Gold Savings Accounts Function
While specific terms vary by financial institution, most bank-run gold accounts share similar mechanics:
While the convenience of managing paper gold alongside your checking account is appealing, it does not provide the safety of direct metal ownership.
To understand how bank products operate in practice, consider the United Overseas Bank (UOB) Gold Savings Account (GSA) in Singapore—one of the region's most prominent bank gold products.
Operating Mechanics
Under UOB's published account terms, a GSA requires a minimum opening balance of 5 grams, which must be maintained to keep the account active. Transactions occur in gram increments at prices set unilaterally by the bank, incorporating its own internal profit margin.
Account holders are also charged an ongoing administrative fee: 0.25% per annum of the highest monthly gold balance plus GST.
It is vital to note the difference between UOB’s GSA and its physical bullion sales counter. UOB sells actual physical gold bars and coins directly as a separate product line. Buying a physical bar at the main branch counter grants immediate physical possession and absolute title. Holding a balance in the GSA does not.
Converting Digital GSA Balances to Physical Gold
While converting a UOB GSA balance into a physical gold bar is technically permitted, it comes with rigid constraints:
Understanding the difference between allocated and unallocated gold is essential when evaluating any precious metals product. This legal distinction dictates whether you are a direct owner of physical property or simply an unsecured creditor to a corporation.
What Is Allocated Gold?
Allocated gold refers to specific, physically identifiable bars or coins that are segregated and registered directly in your name.
What Is Unallocated Gold?
Unallocated gold represents a general claim against a provider for an equivalent amount of metal.
The Deposit Insurance Fallacy
A common misconception among bank clients is that a bank-administered gold account is protected by national deposit guarantee schemes, such as Singapore’s Deposit Insurance Scheme (SDIC) or the UK’s Financial Services Compensation Scheme (FSCS).
Gold savings accounts are not currency deposits. Consequently, they are entirely excluded from government deposit insurance guarantees. If a bank fails, an unallocated gold account holder stands in line alongside general creditors without safety nets.
The structural layers separating investors from real metal extend beyond traditional bank savings accounts. Similar paper gold structures operate across global capital markets:
Gold Accumulation Plans (GAPs)
Popular across Asia, Gold Accumulation Plans allow investors to buy small dollar or gram amounts on a recurring monthly schedule. While marketed as simple savings tools, most GAPs operate on an unallocated basis during the accumulation phase, exposing buyers to ongoing counterparty risk until large conversion thresholds are met.
Gold Savings Funds and Fund-of-Funds
Products such as the Nippon India Gold Savings Fund in India introduce multiple layers of financial intermediation between the investor and the underlying commodity:
With three distinct legal structures sitting between you and the physical metal, every layer introduces administrative expense ratios, management fees, and complex operational dependencies. Crucially, fund investors almost never possess the right to redeem their units for physical gold bars.
For investors seeking genuine wealth preservation without counterparty risk, dedicated Bullion Savings Programmes (BSPs)—such as the one offered by physical dealer BullionStar—provide an alternative model built on total transparency and direct ownership.
1. Instant Allocation from Day One
Unlike bank accounts that treat your holding as an unallocated liability, a dedicated BSP physically allocates metal from the moment you purchase as little as 1 gram. The physical backing is fully auditable, with inventory metrics published transparently.
2. Dramatically Lower Storage Fees
Bank gold savings accounts can incur heavy administrative fees. UOB, for instance, charges 0.25% per annum (plus GST) on the highest monthly balance. By contrast, specialized vaulting facilities like BullionStar offer physical gold storage within their BSP at just 0.09% per annum, representing a cost reduction of more than half without hidden account maintenance floors.
3. Transparent, Disclosed Spreads
Bank gold accounts typically embed their profit margins quietly within the quoted buying and selling rates. A professional bullion provider displays live, transparent buy-sell spreads and premiums openly on every product page, updated in real time alongside international spot markets.
4. Direct, Cost-Free Physical Redemption
Reaching a 100-gram threshold in a bank account often triggers undisclosed, discretionary bank conversion fees. Within a true physical BSP, reaching 100 grams of gold (or 15 kilograms of silver) allows you to convert your digital accumulation into an exact physical bar 100% free of charge.
Once converted, you can take physical delivery, pick up your metal in person at a secure retail centre, or leave it vaulted safely in a high-security jurisdiction.
5. Automated Dollar-Cost Averaging
Combining an allocated savings programme with automated purchasing tools (such as AutoInvest) enables you to build a physical metal holding systematically. By automatically acquiring gold at set intervals, you smooth out market volatility without incurring the counterparty risk inherent in paper banking products.
What is a gold savings account?
A gold savings account is a specialized bank product that tracks the international spot price of gold, allowing account holders to buy and sell gram-denominated balances via internet or mobile banking. While convenient, it represents an unallocated claim against the bank rather than direct ownership of physical metal.
Is a bank gold savings account allocated or unallocated?
Most bank gold savings accounts—including UOB’s Gold Savings Account—are unallocated. Account holdings are not segregated into specific, numbered bars in your name. Converting your digital balance into physical bullion requires an explicit, separate request subject to bank approval, minimum thresholds, and extra fees.
Can I convert a gold savings account into physical gold?
With accounts like UOB’s GSA, physical conversion is possible once you accumulate 100 grams. However, it must be settled with non-CPF funds, completed in person at a specific branch, and subject to a discretionary fee set by the bank. Many other paper gold funds and accumulation plans do not allow physical redemption at all.
What fees do gold savings accounts charge?
Bank accounts typically charge annual administrative fees (such as 0.25% p.a. plus tax on the highest monthly balance) alongside an unstated buy-sell spread built into the exchange rate. Fund-based products may also charge ongoing expense ratios that erode returns over time.
Are gold savings accounts safe if a bank fails?
No. Gold savings accounts are non-currency assets and are not protected by deposit insurance schemes like Singapore's SDIC or the UK's FSCS. Because unallocated account balances sit on the bank’s general balance sheet, account holders are treated as unsecured creditors during an insolvency.
What is the minimum purchase required to start a bullion savings plan?
While bank accounts often enforce minimum opening thresholds (such as 5 grams for UOB), physical Bullion Savings Programmes allow you to start accumulating allocated gold from as little as 1 gram, making real metal ownership accessible to every budget.
The choice between a bank gold savings account and direct bullion ownership comes down to your primary goal. If you are seeking short-term price exposure within a familiar banking interface, a bank account offers basic convenience.
However, if your objective is true financial protection, risk mitigation, and long-term wealth preservation, unallocated bank products fall short.
By choosing an allocated Bullion Savings Programme, your gold is physically secured in your name from the very first gram, free from banking counterparty risks, and ready for physical redemption whenever you choose.
Disclaimer: This article is provided for informational purposes only, mistakes may be made, and it's not offered or intended to be used as legal, tax, investment, financial, or any other advice.