x



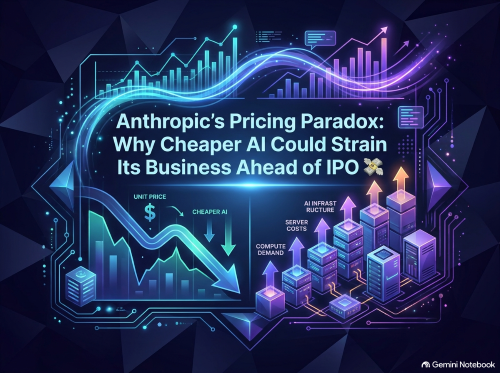
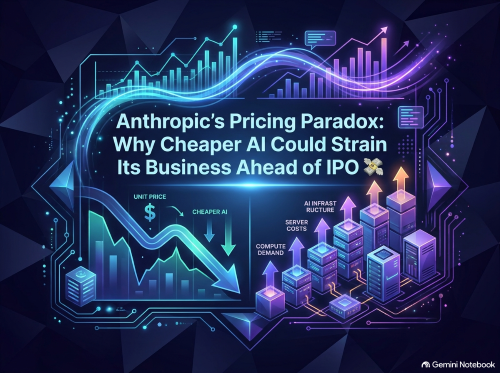
For artificial intelligence developers, lowering the cost of intelligence has long been heralded as the ultimate goal. When AI models become cheaper, faster, and more efficient, adoption skyrockets across enterprises and software applications. Yet for Anthropic, the pioneer behind the Claude model family, making its technology vastly more affordable is creating an intricate financial puzzle just as it prepares for its initial public offering on the Nasdaq.
While Claude's usage rates continue to surge, the company faces a demanding economic equation: its computing expenditures grew faster than its top-line sales in the latest quarter. Managing lower unit prices alongside rising infrastructure costs presents a complex balancing act for a firm stepping into the glare of public market scrutiny.
Over recent months, Anthropic has unveiled substantial price cuts across its flagship offerings. Models like Claude Fable 5.1 have dramatically slashed the cost of typical customer workloads by approximately 25 per cent, with savings reaching up to 45 per cent on highly agentic, context-heavy tasks. This reduction was primarily driven by cutting input cache-read pricing to $0.25 per million tokens, as highlighted in Anthropic's official model launch announcement. Similarly, Claude Opus 5.5 reduced the cost per task for enterprise clients by around 40 per cent compared to Opus 5.
From a product perspective, the commercial rationale is straightforward: cheaper models lower the barrier to entry, prompting organisations to run longer, more complex workflows and integrate AI deeper into daily operations. However, from a financial perspective, these price cuts carry immediate trade-offs.
In its recent disclosures, Anthropic revealed that revenue expansion from increased customer usage was partially offset by a reduction of approximately $600 million resulting from new model price cuts and contractual discounts. As explored in a detailed analysis on Decrypt, these figures do not represent lost revenue, but rather the massive volume of potential top-line growth absorbed by aggressive pricing adjustments aimed at keeping Claude competitive in a crowded market.
The core challenge facing Anthropic stems from a widening divergence between infrastructure spend and revenue growth. In the third quarter, compute and infrastructure expenses surged by roughly 77 per cent, rising from $5.56 billion to $9.86 billion. Over the same period, quarterly revenue grew by 47 per cent to $16.96 billion.
This margin compression means Anthropic spent approximately 58 cents on compute and infrastructure for every dollar of revenue generated in the third quarter—up from 48 cents per dollar just three months earlier. Because compute calculations include research, model pre-training, and internal operations alongside customer-facing inference, the company's overall operational margins experienced a noticeable squeeze.
A key factor driving this margin shift was $5 billion in short-term compute commitments secured during the quarter, which carried significantly higher unit costs than capacity locked in under multi-year contracts. As documented in Anthropic's amended SEC S-1 filing, these elevated short-term expense burdens contributed to an operating loss of $567 million in the third quarter, swinging from an operating profit of $974 million in the second quarter.
Looking beyond immediate quarterly results, Anthropic’s long-term financial landscape is dominated by enormous infrastructure obligations. The company has entered into aggregate purchase commitments and lease agreements totalling approximately $895.4 billion, almost entirely dedicated to compute capacity and data centre infrastructure. Of this monumental sum, roughly $447.5 billion is scheduled to be spent before the end of 2030, with $69.8 billion due within the next 12 months alone.
Securing such massive computing power requires complex supply chain arrangements with cloud service providers and hardware manufacturers. In its regulatory disclosures, Anthropic explicitly flagged potential risks surrounding whether its partners can secure the necessary credit and capital to deliver this contracted capacity on schedule.
As detailed in coverage by Reuters, Wall Street analysts are closely scrutinising how these long-term spending commitments align with future revenue growth. Because compute capacity must typically be reserved 12 to 18 months in advance, spending remains relatively fixed even when market pricing structures or customer usage patterns shift.
Despite these operational pressures, Anthropic's underlying commercial adoption remains exceptionally robust. Enterprise demand has scaled at an extraordinary pace, with the company counting more than 11,900 enterprise customers generating at least $100,000 in trailing twelve-month revenue—up from around 1,500 late last year. Furthermore, its Net Revenue Retention stands near an impressive 900 per cent, reflecting deep satisfaction among existing corporate clients who continually expand their deployments of tools like Claude Code and Claude Cowork.
As Anthropic prepares to list under the ticker "ANT" on the Nasdaq, investors will be weighing two competing dynamics. On one hand, Claude remains one of the world's premier frontier models, backed by unprecedented enterprise momentum and recursive research capabilities. On the other hand, the company must demonstrate that it can reduce model costs for users while keeping its own compute expenses under control.
The ultimate test for Anthropic will be whether model efficiency gains and compounding customer volume can eventually outpace the enormous cost of building, training, and hosting frontier artificial intelligence at global scale.
Disclaimer: This article is provided for informational purposes only, mistakes may be made, and it's not offered or intended to be used as legal, tax, investment, financial, or any other advice.