x



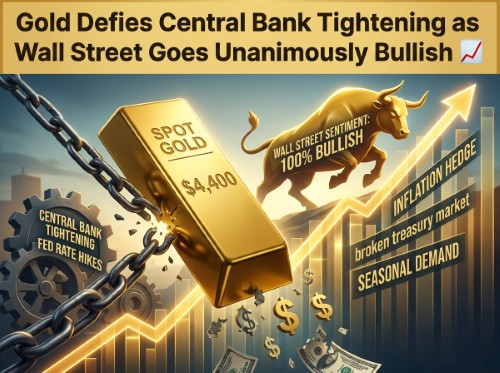
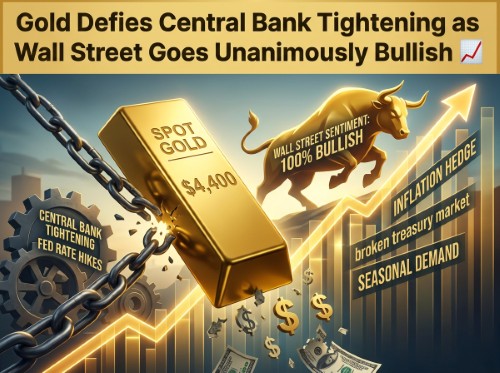
In a week defined by heightened market volatility, gold has demonstrated remarkable resilience. Despite facing immense downward pressure from surging crude oil prices, rising Treasury yields, and an aggressive Federal Reserve, the precious metal managed to reverse its losses, snap a three-week losing streak, and cross back above the critical $4,300 per ounce threshold.
The recovery has reignited institutional optimism. Market participants across Wall Street have adopted an overwhelmingly bullish stance, setting the stage for what could be a powerful fourth-quarter rally.
The trading week initially presented a daunting backdrop for precious metals. Spot gold opened under strain, falling to a one-month low near $4,279.30 per ounce as traders braced for tighter monetary policy alongside renewed Middle Eastern tensions and climbing energy costs.
The pressure intensified when the Federal Open Market Committee (FOMC) delivered a anticipated quarter-point rate increase, bringing the target range to 3.75%–4.00%. The update signalled that a vast majority of policymakers still anticipate further tightening before the year ends. Gold briefly dipped to a weekly low of $4,261.80 per ounce following the announcement.
However, the sell-off proved short-lived. As crude oil prices began a three-day slide and Treasury yields eased off their local peaks, gold launched a swift counter-offensive. The yellow metal rallied to a weekly high of $4,400.60 per ounce before settling near $4,377 per ounce—finishing the week firmly in positive territory and signalling that bears have lost their momentum.
To unseasoned observers, gold’s post-hike surge might seem paradoxical. Higher interest rates typically increase the opportunity cost of holding non-yielding bullion, bolstering the US dollar at gold’s expense. However, several macroeconomic factors transformed this textbook reaction into a classical "sell the rumour, buy the news" event.
1. Market Expectations Were Fully Priced In
Traders had already discounted the 25-basis-point increase well before the FOMC convened. Once the decision became official, short sellers were forced to cover their positions, providing an immediate floor for spot prices.
2. Negative Real Returns
With official benchmark interest rates at 4.00% and baseline consumer price figures hovering near 3.4%, traditional cash returns offer minimal real yield. Furthermore, consumer sentiment reflects an effective inflation rate far higher than official statistics suggest. When adjusted for real purchasing power loss, holding fiat currency yields a negative return, making physical gold significantly more appealing to asset allocators.
3. Central Bank Inaction Window
Historically, the Federal Reserve avoids making major policy shifts immediately prior to major geopolitical events or domestic elections. With political campaigns accelerating globally, analysts anticipate that the central bank will likely hold rates steady until the final weeks of the year, granting gold a clear run through the autumn.
Beyond interest rate expectations, deeper structural vulnerabilities in global finance are compelling investors to seek sanctuary in real assets.
Treasury Market Fragility
Signalling from financial authorities suggests that the US Treasury market is enduring structural stress. When sovereign debt markets exhibit elevated volatility, confidence in paper assets declines. Gold acts as the ultimate counterparty-risk-free asset during periods when sovereign bond markets struggle to maintain stability.
Energy Dynamics and Geopolitics
While high oil prices briefly weighed on gold by stoking broader rate-hike fears, any sudden easing in crude pricing acts as a relief valve for consumer sentiment, allowing precious metals to trade on fundamental safe-haven merits. Conversely, lingering diplomatic stalemates in the Middle East and shipping disruptions continue to embed a persistent geopolitical risk premium into hard commodities.
The shift in market sentiment following gold's mid-week stabilisation has been decisive.
From a technical chart perspective, gold’s ability to defend the $4,300 region marks a pivotal structural turning point.
As the calendar turns toward the final quarter of the year, seasonal buying patterns traditionally offer an additional tailwind for precious metals. High-volume physical purchasing across Asia—driven by major cultural events, festivals such as Diwali, and wedding season demand—frequently drives physical tightness in spot markets from late September through October.
When seasonal physical demand aligns with supportive macroeconomic conditions and geopolitical uncertainty, historical trends favour sustained upward momentum.
Gold’s impressive recovery following an explicit Federal Reserve rate hike highlights a fundamental shift in market regime. Investors are increasingly looking past nominal interest rate policy and focusing instead on fiscal deficits, persistent inflationary pressures, and sovereign debt risks.
With $4,300 established as a formidable floor, Wall Street turning unanimously optimistic, and seasonal physical demand ramping up, gold appears well-positioned to challenge new historic highs as the year progresses.
Disclaimer: This article is provided for informational purposes only, mistakes may be made, and it's not offered or intended to be used as legal, tax, investment, financial, or any other advice.