x



Imagine ordering a hot lunch through a delivery app on your phone, tapping a screen, and paying instantly with digital US dollars, all without touching a traditional bank or visiting a currency exchange counter. For millions of people across Latin America, that scenario used to sound like distant science fiction. Today, in Bolivia, it is fast becoming an everyday reality.
Following years of severe foreign exchange shortages and currency restrictions, Bolivia is rapidly turning into one of the most exciting testing grounds for stablecoin adoption. Rather than using crypto simply to store savings or speculate on market price swings, Bolivian consumers and local merchants are now using Tether (USDT) to buy groceries, order takeaways, and access instant micro-loans.
Here is how strategic investments from industry leaders like Tether and innovative fintech partnerships are bringing stablecoin payments straight into Bolivia's banking rails and high-street counters.
To understand why stablecoins are taking off so rapidly in Bolivia, it helps to look at the economic backdrop. For years, the country grappled with fixed exchange rates, strict currency controls, and a persistent shortage of physical US paper dollars. In 2024, the Central Bank of Bolivia lifted its four-year ban on digital asset transactions, granting the financial system room to breathe.
The response from the public was immediate. Crypto trading volumes surged by more than 600 per cent in early 2025, with citizens eager for a stable store of value to protect their purchasing power against inflation. Recognising the massive public shift, local monetary authorities began exploring ways to formalise this digital economy.
Bolivia's Minister of Economy and Public Finance, Jose Gabriel Espinoza, revealed that the government is actively assessing how to incorporate USDT alongside the Bolivian boliviano and the US dollar. As highlighted in Bitcoin.com News' report on Bolivia's financial system evaluation, officials are looking at framework regulations that would allow stablecoins to settle debts and operate seamlessly within commercial bank accounts. Commercial institutions like Bisa Bank have already begun stepping up to offer USDT exchange services, signalling a major transition towards mainstream financial integration.
While policy discussions continue at the government level, practical everyday infrastructure is already being built on the ground. Tether, the issuer behind USDT, recently led a pre-seed funding round in Peso, a Bolivian fintech startup dedicated to building frictionless stablecoin infrastructure.
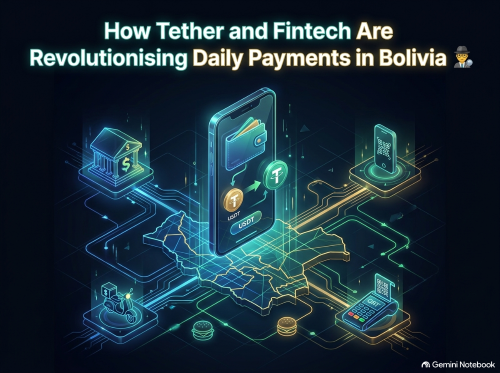
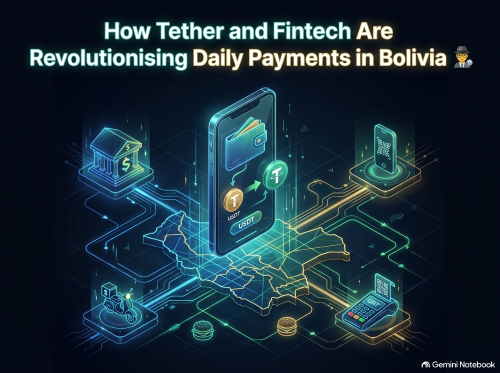
Peso’s goal is simple: eliminate the hassle of converting crypto into local fiat every time someone wants to buy something. Through Peso's technology, users can hold a global USDT account to save, transfer, and make retail purchases directly.
One of the most impressive real-world implementations is Peso’s partnership with Yango, a popular digital services platform in Bolivia. Users can now order food delivery and pay for their meals directly in USDT inside the app. On top of that, Peso is rolling out a network of point-of-sale (POS) merchant terminals, virtual bank accounts, and QR-code payment integrations connected to Bolivia’s national banking rails via ACH transfers. This allows stablecoin balances to connect directly to local financial accounts.
According to Cointelegraph’s coverage on Tether backing Bolivian fintech, this strategic backing is designed to expand across four key Latin American markets: Bolivia, Brazil, Colombia, and Argentina.
In an official statement on Tether's announcement of its Peso investment, Tether CEO Paolo Ardoino emphasised that Peso is creating the exact type of daily-spend infrastructure needed to transform USDT from a passive savings reserve into an active, everyday payment network.
Paying for food and retail goods in stablecoins solves a huge piece of the daily transactional puzzle, but access to credit remains another monumental hurdle in emerging markets. According to international labour data, more than 80 per cent of workers in Bolivia operate within the informal economy. Because traditional banks require formal employment contracts and extensive paperwork, millions of hard-working individuals have historically been locked out of traditional bank loans.
To tackle this issue, AI-native credit platform Tala partnered with El Dorado, a prominent digital wallet serving over one million users across Latin America. As detailed in Tala's blog on embedded credit in El Dorado, the collaboration brings instant, underwritten micro-credit straight into the wallet interface.
Eligible users can choose their own loan terms and receive funds in seconds. Crucially, borrowing and repayments occur directly in USDT on the Tempo blockchain. By using alternative behavioural data to assess creditworthiness, this system allows market vendors, freelancers, and small business owners to build a credit history and access funds during slow months without relying on pawn shops or high-interest informal lenders.
What is happening in Bolivia represents a fundamental shift in how digital assets are perceived and used globally. Stablecoins are no longer just an asset class for crypto traders; they are becoming essential utility tools for everyday financial survival, commerce, and credit.
By uniting supportive regulatory shifts, local fintech innovation like Peso and El Dorado, and global capital from backers like Tether and Tala, Bolivia is building a blueprint for financial inclusion. As these payment rails mature, paying for your morning coffee or securing a business loan in digital dollars could soon be as routine as tapping a contactless card.
Disclaimer: This article is provided for informational purposes only, mistakes may be made, and it's not offered or intended to be used as legal, tax, investment, financial, or any other advice.