x



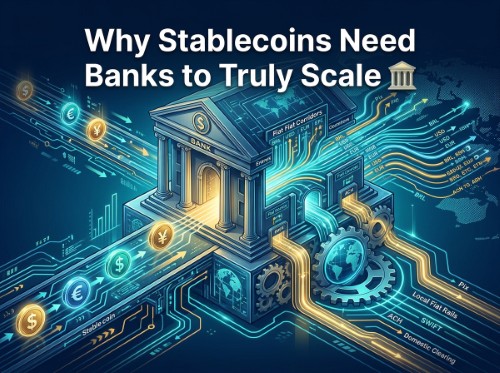
For years, the core promises of cryptocurrency revolved around disintermediation: bypassing legacy financial institutions, eliminating friction, and building an entirely parallel global financial network. Yet, as institutional interest in digital assets reaches an all-time high, an intriguing paradox has emerged. Rather than dismantling traditional financial infrastructure, the companies successfully scaling stablecoins are embedding themselves deeper within the banking sector than ever anticipated.
While multi-trillion-dollar transaction statistics dominate industry headlines, genuine enterprise payment flows tell a vastly different story. For stablecoins to evolve from a niche settlement mechanism into the foundation of global commerce, they must embrace, integrate with, and rely upon traditional banking networks.
Headline figures claiming that annual stablecoin transaction volumes exceed tens of trillions of dollars obscure a critical distinction. The vast majority of on-chain volume is driven by high-frequency trading bots, decentralized finance (DeFi) liquidity pools, and exchange arbitrage.
When evaluating genuine real-world payments—such as corporate payroll, vendor invoices, and cross-border trade—the actual numbers are far more modest. By late 2025, genuine stablecoin payment volume ran at an annualised rate of roughly $390 billion. While impressive given the industry's youth, this represents a mere 0.02% of the staggering $208 trillion global cross-border payments market.
The massive gap between speculative on-chain activity and real enterprise utility highlights a fundamental reality: corporate finance does not originate on the blockchain.
To understand why traditional banks remain indispensable, one must examine how cross-border value actually moves. An enterprise payment across international borders consists of three distinct legs:
Stablecoins excel at solving the middle leg by introducing speed, 24/7 availability, and programmability. However, the first and third legs remain strictly within the domain of traditional banks. Because enterprise treasuries, tax authorities, and payroll systems operate in fiat, banks remain the non-negotiable compliance anchors and local rail gateways at both ends of every transaction corridor.
Processing $50 million in annual stablecoin volume is relatively simple; a startup can rely on a single banking counterparty, one stablecoin issuer, and a basic compliance wrapper. However, scaling to $500 million or $10 billion exposes severe structural bottlenecks.
At institutional scale, payment processing is no longer a pure software challenge—it becomes a regulatory, foreign exchange (FX), and multi-jurisdictional banking challenge. Enterprise customers demand seamless liquidity across dozens of fiat corridors.
Consider Brazil’s instant payment platform, Pix, which moved over R$35 trillion (approximately $6.3 trillion) in a single year, with B2B transactions accounting for nearly half of that total. Tapping into such immense liquidity requires direct integration with local banking rails, sophisticated FX conversion architecture, and deep regulatory licencing across every operating jurisdiction. The underlying blockchain tech operates flawlessly, but growth inevitably stalls when companies fail to build the necessary banking infrastructure beneath it.
Single-bank dependency represents one of the most underappreciated operational risks in digital asset payments. Relying on a single primary banking partner leaves a payment provider vulnerable to sudden debanking, regulatory policy shifts, or changes in a bank's internal risk appetite.
The wind-down of Silvergate and the receivership of Signature Bank served as stark warnings to the industry. Subsequent regulatory friction, including formal FTC warning letters regarding debanking practices and executive orders addressing fair banking access, further demonstrate how volatile single-point connections can be.
When a provider loses its sole banking partner, its payment operations grind to an immediate halt. Building a resilient, enterprise-grade architecture requires true banking depth: multiple redundant banking connections, robust multi-currency FX facilities, and a compliance model tailored to meet the strict standards of international regulators.
In the early days of crypto, compliance was frequently viewed as friction to be avoided. Today, for corporate CFOs, institutional treasurers, and tier-one financial exchanges, rigorous compliance is a non-negotiable prerequisite.
Regulatory developments, such as the US GENIUS Act passed in mid-2025, have established stringent bank-grade reserve, disclosure, and licensing standards for stablecoin issuers. These regulatory frameworks actively direct high-volume institutional flows toward bank-backed structures and fully compliant entities.
While market surveys indicate that over 80% of non-using financial institutions are actively exploring stablecoin adoption, their primary hurdle remains trust. Stablecoin platforms that prioritise licencing depth, multi-bank redundancy, and defensible compliance frameworks will capture the vast majority of institutional enterprise market share.
The future of global payments does not belong to stablecoins operating in isolation, nor does it belong to legacy correspondent banking systems unchanged by technological progress. Instead, the winning model combines the strengths of both worlds:
Major market moves—such as payment giant Stripe acquiring orchestration layer Bridge for $1.1 billion, or traditional titans like Citi and Standard Chartered rolling out digital asset custody and stablecoin settlement services—signal a clear industry direction. The digital asset platforms achieving true enterprise scale are doing so by integrating directly into the banking ecosystem, creating a hybrid financial infrastructure built for long-term endurance.
Disclaimer: This article is provided for informational purposes only, mistakes may be made, and it's not offered or intended to be used as legal, tax, investment, financial, or any other advice.