x



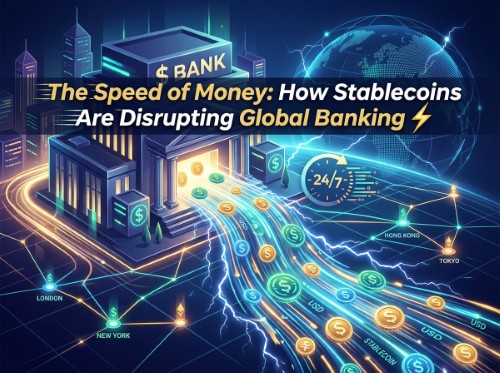
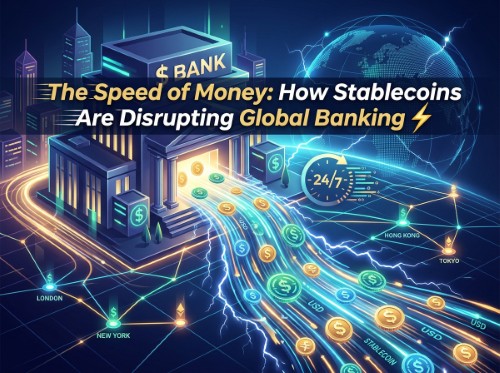
Anyone who has ever initiated an international bank transfer understands the quiet frustration of legacy finance. Between correspondent banking fees, conversion markups, and restrictive operating hours, cross-border payments often feel stubbornly antiquated. In an era where data travels instantaneously across the globe, moving money across borders can still take several business days.
Enter stablecoins. By pegging digital tokens to fiat currencies like the US dollar and settling transactions on borderless blockchains, stablecoins bypass traditional clearing houses entirely. They operate 24 hours a day, seven days a week, settling transactions in seconds rather than days.
However, this unprecedented speed brings profound implications for commercial banks, central bank policy, and national economies. Real-time liquidity offers transformative efficiency for global commerce, but it also creates structural vulnerabilities that traditional financial institutions are only beginning to comprehend.
To appreciate the disruptive force of stablecoins, one must look at where friction sits in the traditional banking architecture. When funds move internationally via traditional rails like SWIFT, they pass through a chain of intermediary correspondent banks. Each link adds delays, administrative overhead, and cost.
Stablecoins eliminate this friction by acting as a universal bearer asset on public distributed ledgers. They allow businesses and individuals to store and transfer digital dollars without requiring a traditional bank account or waiting for legacy systems to open on Monday morning.
Yet, this real-time speed introduces a fundamental paradox: money can now move faster than the banking architecture that underpins it.
The impact of stablecoins on global banking operates across two distinct temporal dimensions—often referred to as the "two clocks."
1. The Slow Clock: Stealth Dollarisation and Deposit Erosion
The slow clock represents a gradual, structural shift that unfolds over months and years. In economies facing persistent inflation, currency depreciation, or strict capital controls—such as Argentina, Turkey, or Nigeria—citizens increasingly seek refuge in digital dollars.
Historically, obtaining physical greenbacks or opening a foreign currency bank account required overcoming significant regulatory or logistical hurdles. Today, a smartphone and an internet connection are all that is required to swap volatile local fiat into dollar-pegged stablecoins.
This steady migration weakens local monetary policy. As domestic capital leaves local commercial bank accounts to reside in digital dollar wallets, central banks lose traction over interest rates and credit conditions. Over time, commercial lenders face deposit erosion, reducing their capacity to extend credit into the local economy.
2. The Fast Clock: Software-Speed Capital Flight
If the slow clock is a steady drip, the fast clock is a sudden surge. This phenomenon occurs during financial panics, issuer crises, or geopolitical tensions, where capital moves at the speed of software within hours or minutes.
Because stablecoins settle around the clock, capital flight can occur outside standard banking hours. During weekends or bank holidays, when traditional foreign exchange markets and domestic wire transfers are closed, blockchain networks remain open. If domestic confidence falters, billions in value can convert into digital assets before central bankers or regulators have an opportunity to react.
The intersection of these two clocks highlights a critical weakness in modern finance: a structural liquidity mismatch.
Most major stablecoin issuers back their tokens with short-term government debt and cash deposits held inside commercial banks. While the stablecoin itself trades and settles 24/7 on-chain, the underlying bank deposits and Treasury bills supporting its value remain bound by traditional settlement timelines.
This dynamic was vividly illustrated during the banking stresses of March 2023, when USD Coin (USDC) temporarily lost its dollar parity after its issuer disclosed that $3.3 billion of its backing reserves were locked inside the failing Silicon Valley Bank. A traditional banking disruption instantly metastasised into a real-time crypto liquidity shock, sparking widespread redemptions.
Recognising this hazard, regulatory frameworks such as Europe's Markets in Crypto-Assets (MiCA) regulation initially required issuers to keep a substantial portion of their reserves in bank deposits. However, central bankers increasingly worry that fixed deposit rules could force stablecoin issuers to pull vast sums out of commercial banks overnight during a redemption run, inadvertently triggering the very bank runs they aimed to prevent.
Despite concerns that digital dollars will render traditional banks obsolete, current market usage tells a more nuanced story. Stablecoins are not necessarily replacing banks; rather, they are streamlining the financial plumbing connecting them.
In corporate and enterprise settings, stablecoins are primarily utilised as a high-speed settlement layer rather than a long-term store of value:
Commercial banks will continue to play an irreplaceable role in credit creation, regulatory compliance, asset custody, and local fiat integration. However, the profitable intermediary fees historically collected on cross-border wire transfers and currency conversions are facing permanent margin compression.
Stablecoins represent a fundamental upgrade to the mechanics of international value transfer. By allowing money to move with the same ease and speed as digital information, they offer enormous productivity gains for global commerce, international remittance, and financial inclusion.
However, sovereign nations and banking institutions must adapt to a world where financial liquidity operates without a closing bell. Countries that proactively establish clear regulatory guardrails, maintain stable domestic economies, and modernise their own settlement infrastructure will leverage digital dollars as an engine for growth. Conversely, nations that rely on capital controls and rigid banking schedules risk being overwhelmed by the software-speed movement of global capital.
Disclaimer: This article is provided for informational purposes only, mistakes may be made, and it's not offered or intended to be used as legal, tax, investment, financial, or any other advice.